Energy-saving technology adoption is continuing to expand across the merchant fleet, but the strongest momentum remains concentrated around solutions with a proven commercial and operational case.
Hull and propeller technologies continue to lead adoption, while wind-assisted propulsion and software-based optimization are becoming increasingly relevant parts of the efficiency landscape.
Recent data from Clarkson’s Research shows just how significant this shift has been. Hull technology installations increased by 54%, while propeller technologies grew by 42%. Wind technologies increased by 8%, with engine-room technologies growing by 4%.
The numbers point to a broader trend: as regulatory pressure increases and the cost of emissions becomes more tangible, shipowners are continuing to invest in technologies that can deliver measurable efficiency gains across existing vessels and newbuilds.
Proven solutions continue to gain ground
The strongest growth is concentrated around technologies that are already well understood and relatively straightforward to integrate.
Hull Fins increased by 75% to 2,031 vessels, while Rudder Bulbs grew by 58% to 6,982 vessels. Bow Enhancements increased by 56% to 5,091 vessels, with Pre-Swirl Stators and Propeller Boss Cap Fins also recording strong growth.
These technologies have an established performance record and can often be incorporated into retrofit programmes without fundamental changes to a vessel's propulsion system. For shipowners, that combination matters: proven technology, measurable fuel-saving potential and a clear route to implementation.
Wind-assisted propulsion is moving forward
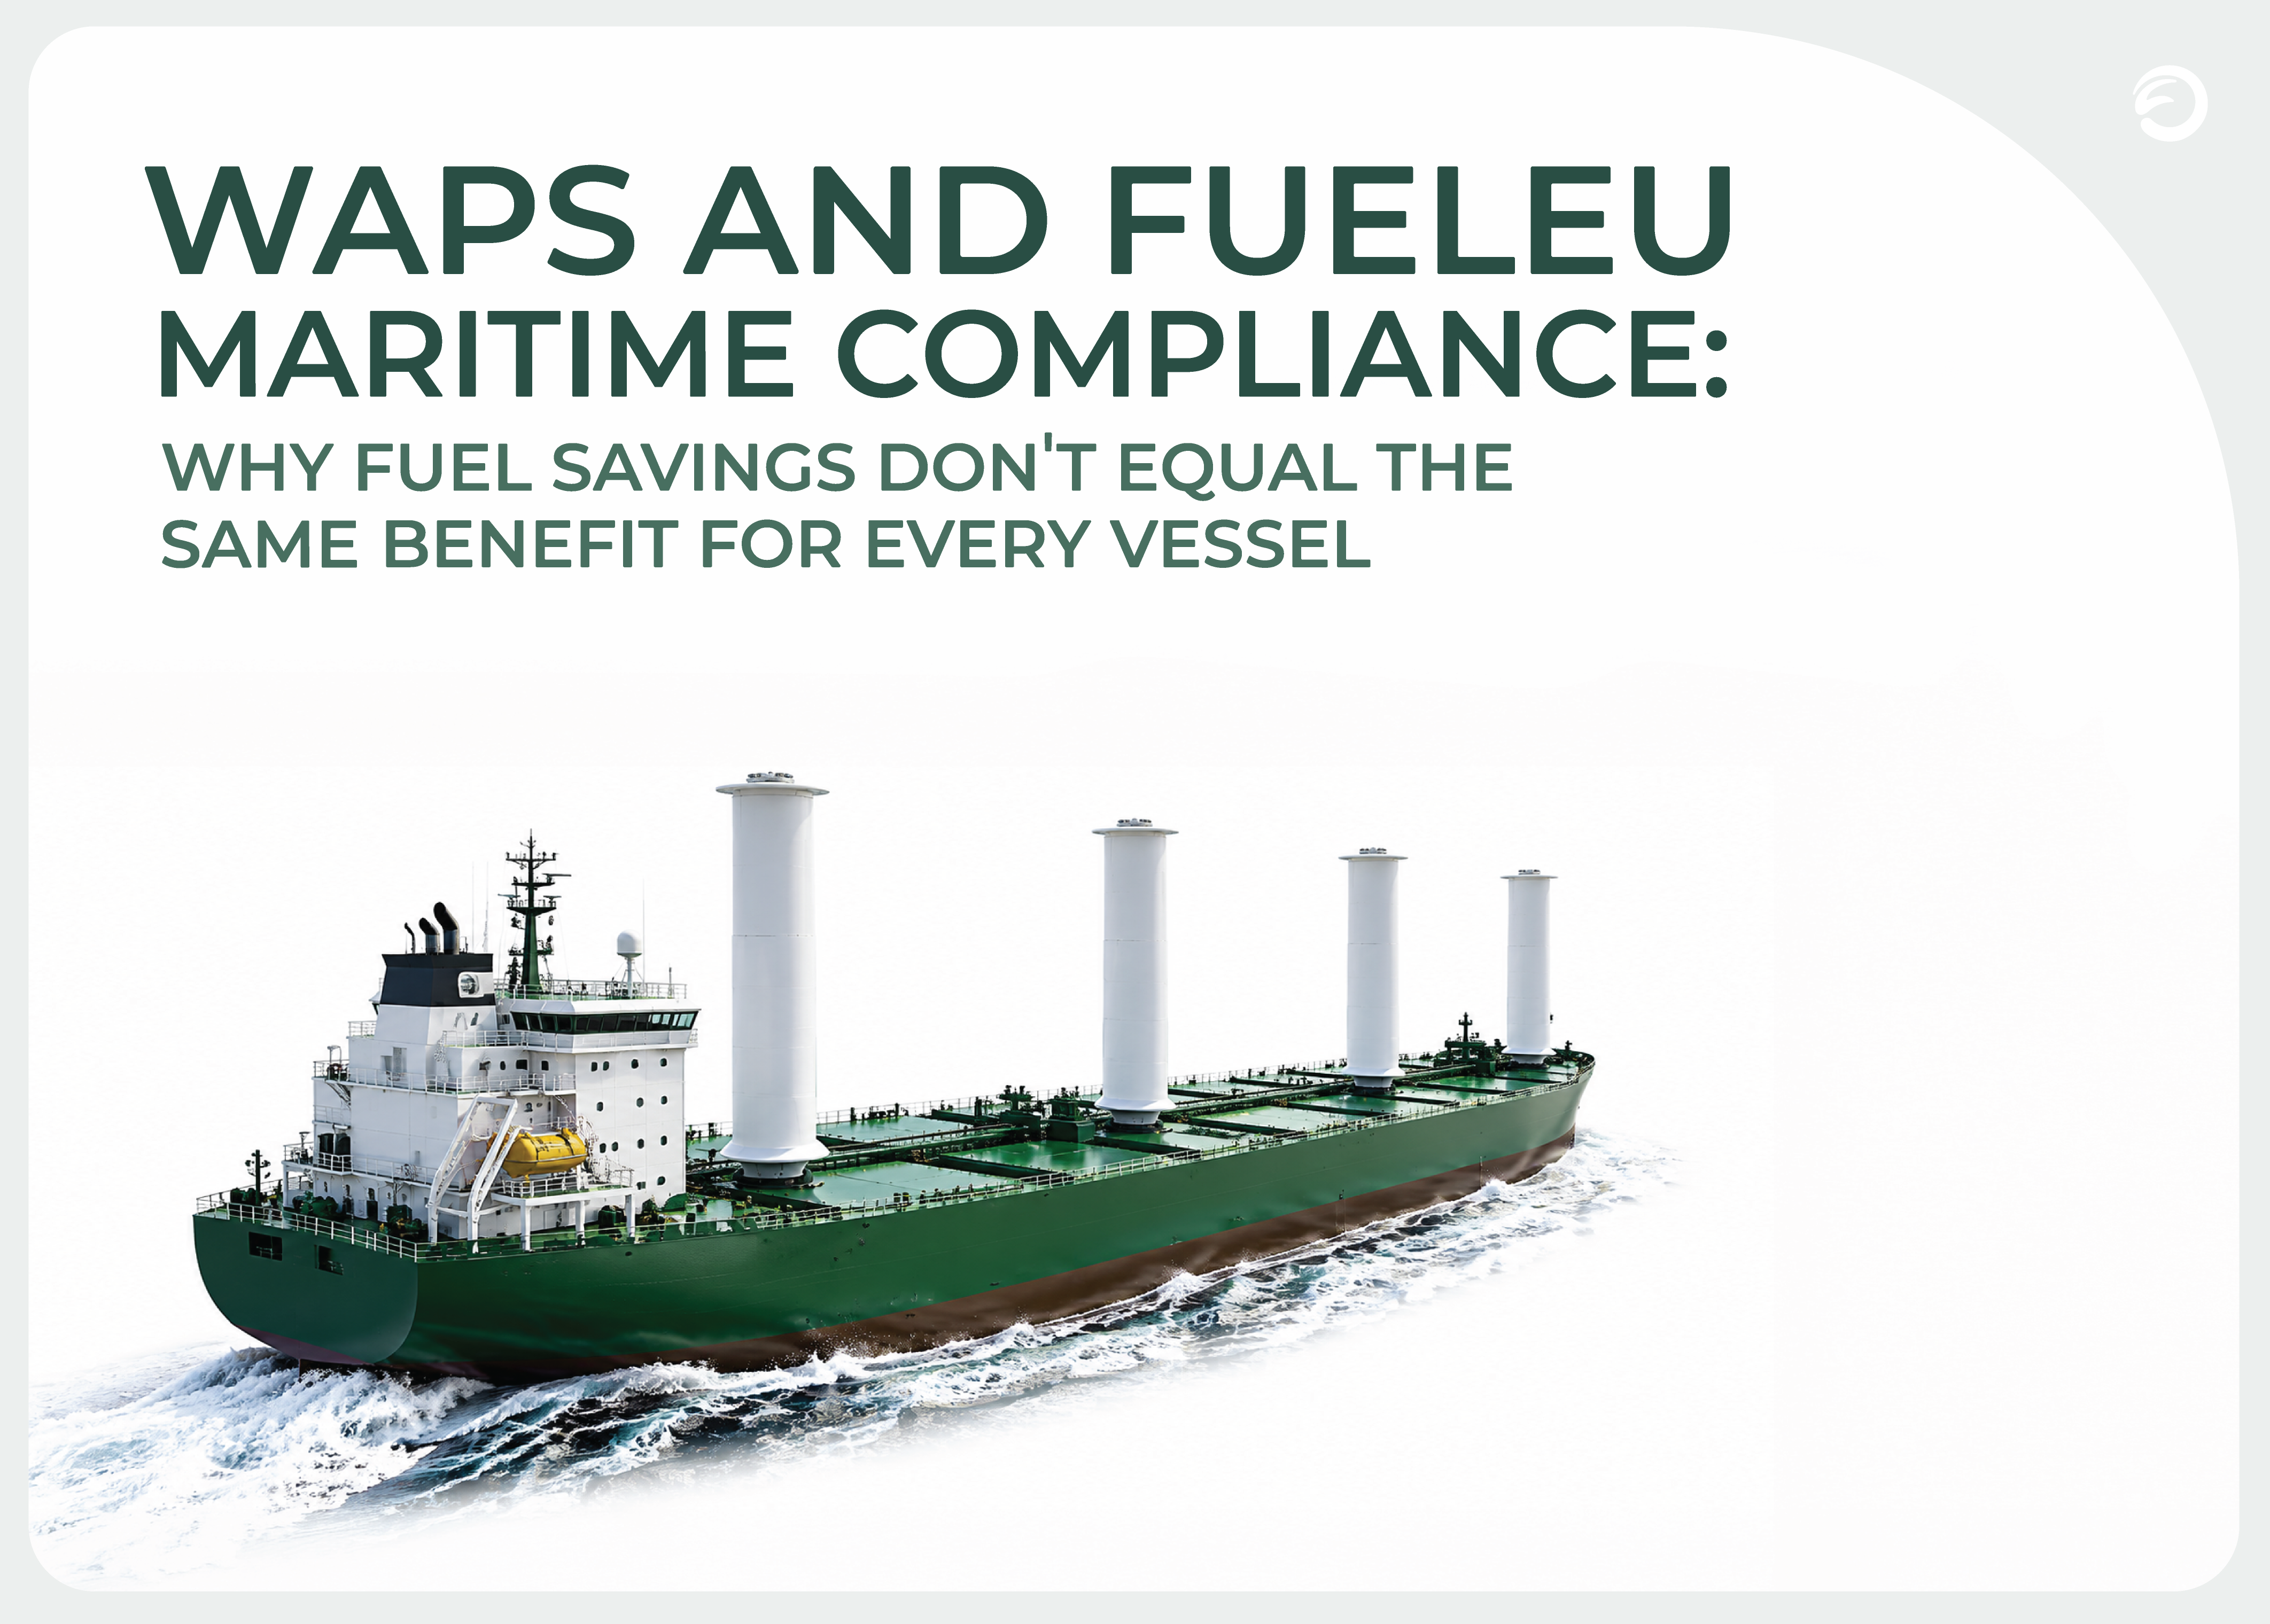
Wind-assisted propulsion remains a smaller part of the installed base, but its trajectory is worth watching. Flettner Rotor installations increased from 51 to 67 vessels, while Rigid Sail installations grew from 38 to 41.
The numbers remain modest compared with conventional hull and propeller technologies. But as more systems move into operation, the industry is gaining more real-world data on where wind assistance works, what it can deliver and which vessel profiles are best suited to it.
As Steen Jacobsen, Technical Director at Njord, notes:
“IWSA data puts wind-assisted and wind-ready adoption up 100% year-on-year, a much steeper curve than the hull and propeller technologies leading this article. What's equally notable is what's happening alongside proven hardware like PBCF and rudder bulbs: software-based operational optimization is maturing quickly, with far more of it being tested and deployed in 2026. For me, that's the real story of 2026, efficiency is no longer just about what's bolted to the hull”
The bigger opportunity is at vessel level
The growing number of available technologies also makes the decision more complex. The question is no longer simply which energy-saving technology is gaining the most traction. It is which combination of measures makes sense for a specific vessel.
Technology’s potential depends on the vessel, its trading profile, operating conditions, existing configuration and investment case. The same solution can therefore produce very different results from one vessel to another.
Jonas Lundqvist Junior Naval Architect at Njord, sees this shift particularly clearly in wind-assisted propulsion:
“While hull and propulsion technologies continue to dominate adoption, wind-assisted propulsion is benefiting from a noticeable shift in industry perception. Operational uncertainty remains part of the discussion, but it is increasingly being viewed as a manageable risk rather than a deal breaker, particularly as regulatory and fuel cost pressures continue to grow”
As the technology landscape expands, the focus is increasingly moving towards understanding what works, where it works and how different measures can work together. That is likely to be one of the defining questions for vessel efficiency going forward.

Related articles